A Complete Guide to Truck Driver Loans: Securing Your Dream Home
Truck drivers qualify for home loans the same as anyone else — the difference is how the income gets read. Mileage pay needs to be averaged over 12 to 24 months, an owner-operator’s per diem deduction has to be read at the trucking rate rather than the usual one, and owner-operators can qualify on bank deposits instead of tax returns. A lender who understands those three things is the difference between a denial and an approval.
Why does trucking income confuse most lenders?
Truck drivers are the backbone of the American economy, but when it comes to securing a mortgage, the road can feel bumpy. At Priority Home Mortgage in Grand Rapids, we understand the financial situations transportation professionals actually face — whether you are paid by the mile, receive per diem allowances, or run as an independent contractor on a 1099:
- Variable income: Mileage pay fluctuates with routes and seasons, so your earnings need to be averaged correctly, not penalized.
- Tax write-offs: Owner-operators often carry significant deductions that lower their qualifying net income on paper.
- Per diem pay: For a company driver it is an expense reimbursement, not income. For an owner-operator, the meals deduction on the return has to be subtracted at the right rate.
Our team tailors the financing to your income structure, so your hard work translates into homeownership instead of paperwork frustration.
What are the best mortgage options for truck drivers?
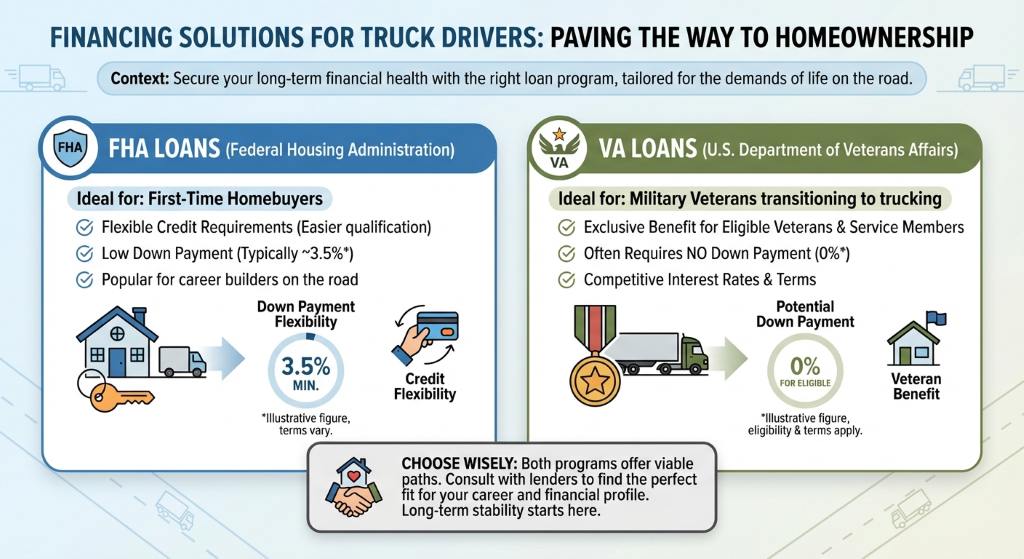
Several loan programs work exceptionally well for drivers:
- FHA loans: Ideal for first-time homebuyers, with flexible credit requirements and a low down payment — a popular choice for drivers who spent their early career on the road.
- VA loans: If you are a military veteran who transitioned into trucking, a VA loan offers a zero-down option and highly competitive interest rates.
- Conventional loans: Great for drivers with strong credit and a steady W-2 history — often the most competitive rates for well-qualified buyers.
- Bank statement loans: For owner-operators and 1099 contractors, these programs use business bank deposits instead of tax returns to verify your true cash flow.
| Employment type | Typical income documentation | Best loan fit | Minimum history required |
|---|---|---|---|
| W-2 company driver | Pay stubs and W-2 forms | FHA, VA, or conventional | 2 years in the same line of work |
| 1099 owner-operator | Tax returns or bank statements | Bank statement loan or FHA | 1 to 2 years of self-employment |
Why work with our Grand Rapids team?
When you are ready to stop renting and start owning, you want a local team that knows the Grand Rapids market inside and out — and that respects your schedule. We know you spend long hours on the road, so our team works around it: collecting documents remotely, answering questions when you are actually reachable, and protecting your closing date.
Whether you are purchasing your first home, expanding an investment portfolio, or refinancing an existing loan, we keep the process simple, straightforward, and fast.
Frequently asked questions
Can I get a mortgage if I am paid by the mile?
Yes. Lenders typically average your mileage pay over the last 12 to 24 months to determine qualifying monthly income. Consistency matters more than any single month.
How does per diem pay affect my loan application?
It depends on how you are paid. For a W-2 company driver, per diem is an expense reimbursement, and most underwriters do not count reimbursements as qualifying income.
For a self-employed owner-operator there is a calculation worth checking. A lender working from your Schedule C subtracts the part of your meal expenses you were not allowed to deduct. Most business owners can deduct 50% of meals, so the undeducted half equals the figure on the return, and underwriters get used to subtracting that figure. Drivers under DOT hours-of-service rules deduct 80% of their meal expenses, so only 20% was left off: one quarter of the figure on the return. Subtracting the full figure understates your income, and for a driver on the road most of the year the difference can be thousands of dollars, depending on your miles.
Are there special home loans for owner-operators?
Owner-operators are considered self-employed. You can use standard loans by providing two years of tax returns, or opt for a bank statement loan that reads your business cash flow instead of your net taxable income.
How long do I need to be a truck driver before buying a house?
Generally, lenders like to see a two-year employment history. If you recently attended a certified truck driving school, that training period can sometimes count toward the requirement.
Can Priority Home Mortgage help me if I live outside of Grand Rapids?
Absolutely. We are proudly based in Grand Rapids, and we help drivers secure competitive financing across the entire state of Michigan and beyond.